


Lumax Auto Technologies lifts FY27 revenue outlook to 20%-25%
Key highlights
- Lumax expects FY27 revenue growth of 20%-25%, implying nearly Rs 6,000 crore of revenue.
- H1 FY27 revenue rose 34% year on year to Rs 2,919 crore, while EBITDA increased 42% to Rs 434 crore.
- Management expects H2 FY27 revenue growth of 15%-20% because of a higher FY26 base.
- Lumax’s Q2 FY27 order book reached Rs 1,879 crore, up from Rs 1,600 crore at the end of Q1 FY27.
powered by IRIS
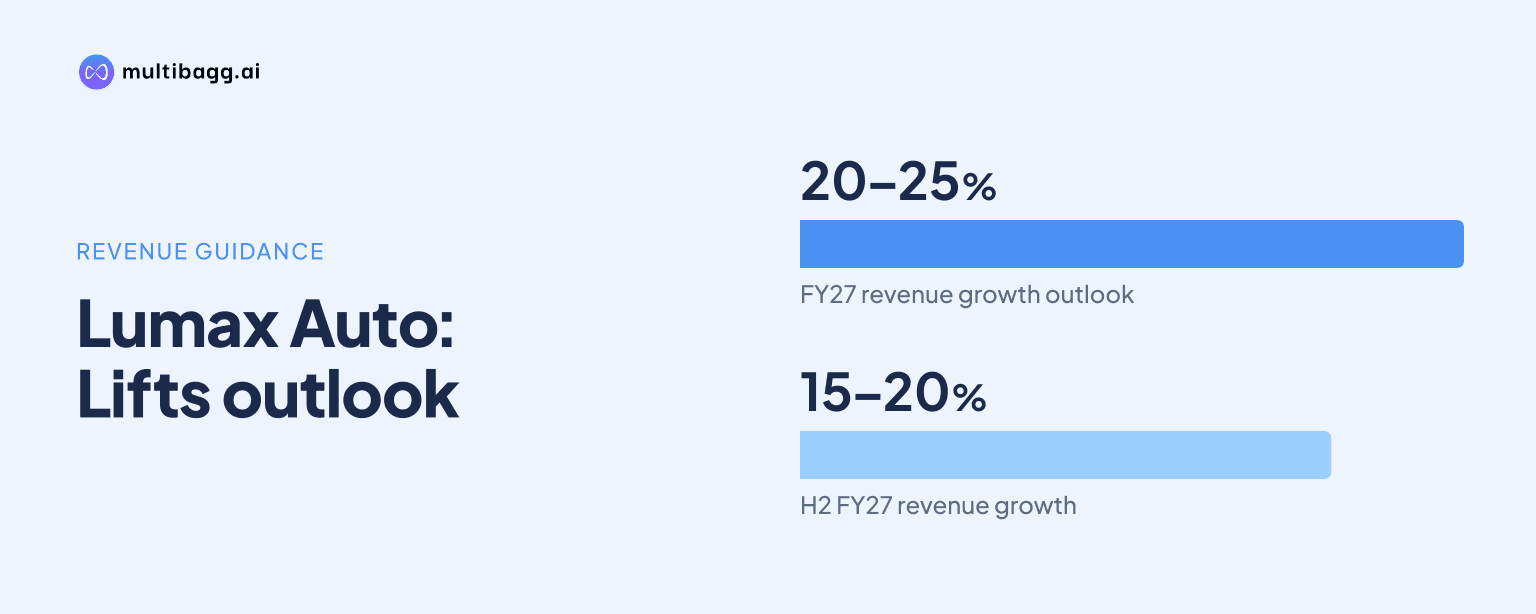
Lumax Auto Technologies Limited expects FY27 revenue to grow 20%-25% year on year and approach Rs 6,000 crore after H1 FY27 consolidated revenue rose 34% to Rs 2,919 crore. Management’s updated range is above the roughly 12%-14% growth implied at the start of the year, when it considered FY26’s 35%-36% growth.
Know Lumax Auto Technologies inside out
Results, valuation, peers and who's buying, in one view.
Why did Lumax raise its FY27 revenue outlook?
Lumax raised its outlook because H1 FY27 performance and automotive-industry demand exceeded the assumptions used at the beginning of FY27. Chief Financial Officer Ankit Thakral said the earlier implied FY27 growth range was about 12%-14%, following FY26 revenue growth of 35%-36% and the company’s objective of delivering about 20% growth across the two years combined.
The revised outlook follows a 35% year-on-year increase in Q2 FY27 revenue to Rs 1,556 crore and a 34% rise in H1 revenue to Rs 2,919 crore. Managing Director Anmol Jain said FY27 revenue growth of 20%-25% would result in revenue close to Rs 6,000 crore, compared with the company’s earlier assumptions for the year.
Lumax has retained its longer-term North Star target of 20% compound annual revenue growth from FY25 to FY31. Management said it aspires to revenue of around Rs 11,000 crore by FY31, with organic execution supplemented by potential strategic inorganic opportunities, and added that it is more confident that 20% organic compound growth could be achievable if industry momentum continues.
What does Lumax expect in the second half of FY27?
Lumax expects H2 FY27 revenue growth of 15%-20% year on year, slower than the 34% reported in H1, because of a higher FY26 comparison base. Management said the lower base in the previous first half contributed to H1 growth and that automotive-sector growth could moderate as the base normalises and the benefit of Goods and Services Tax 2.0 rate cuts is fully reflected in demand.
The automotive industry produced 106 lakh units in Q2 FY27, up 19% year on year, based on Society of Indian Automobile Manufacturers data cited by management. Passenger-vehicle production rose 25% to about 17 lakh units, two-wheeler production increased 17% to 81 lakh units, commercial-vehicle production grew 34% to 3.5 lakh units, and three-wheeler production rose 25% to about 4.5 lakh units.
Management identified the festive season, input costs and original equipment manufacturers’ ability to pass on costs as the main H2 variables. Crude-linked polymer prices, electronic-component costs, freight and rupee depreciation remained monitorable, while management said demand had been aided by improved affordability, rural and urban consumption, freight movement and infrastructure-led activity.
Which Lumax businesses drove first-half revenue growth?
Lumax’s Advanced Plastics and Mechatronics businesses each grew 45% year on year in H1 FY27, the fastest growth among the reported divisions. Advanced Plastics revenue increased by Rs 517 crore to Rs 1,655 crore, supported by the Intelligent Ambient Comfort business, which represented about 60% of the division.
Mechatronics revenue increased from Rs 122 crore to Rs 177 crore, while Alternate Fuels revenue rose Rs 50 crore to Rs 220 crore. Structures & Control Systems grew 24% to Rs 476 crore, but Aftermarket rose only 9% to Rs 234 crore; management attributed the slower Aftermarket growth mainly to lower non-lighting product sales amid higher input costs.
Lumax said its current addressable content per passenger vehicle is about Rs 70,000 to Rs 75,000 and about Rs 20,000 to Rs 22,000 per two-wheeler. Management estimated that Mechatronics accounts for about 20% of passenger-vehicle content today and said products in connected vehicles and vehicle electronic-control-unit interface management could lift that contribution over the next two to three years.
Got a follow-up? Ask IRIS
What supports Lumax’s revenue plan beyond FY27?
Lumax had an order book of Rs 1,879 crore at the end of Q2 FY27, up Rs 279 crore from Rs 1,600 crore at the end of Q1 FY27. Management expects 14% of this order book to be executed in FY27, 59% in FY28 and the remaining 27% in FY29, setting out the disclosed delivery timetable for the awarded business.
Advanced Plastics represented 44% of the Q2 order book, followed by Mechatronics at 27%, Alternate Fuels at 20% and Structures & Control Systems at 8%. About 85% of the total was new business, while compressed natural gas and electric vehicles accounted for 29%, including 20% for compressed natural gas and about 9% for pure electric vehicles; future technologies accounted for another 22%.
On October 24, 2026, the board approved a Mechatronics plant at Manesar, Haryana, with capital expenditure of around Rs 150 crore funded through debt and internal accruals. The facility will manufacture electronic components, including body control modules, is expected to be commissioned in two phases beginning in Q3 FY28, and has a projected peak annual turnover of around Rs 500 crore after commissioning.
Lumax maintained FY27 capital-expenditure guidance of around Rs 300 crore, including greenfield expansion in Mechatronics, Advanced Plastics and Alternate Fuels that is expected to begin start of production in H2 FY27. Separately, Lumax Greenfuel Energy Solutions began production at its Nashik facility in Q3 FY27, supplying ferrule-less tubes, fittings and receptacles to Mahindra & Mahindra.
How are costs and profitability affecting Lumax’s outlook?
Lumax reported H1 FY27 earnings before interest, tax, depreciation and amortisation (EBITDA) of Rs 434 crore, up 42% year on year, with a margin of 14.9%, up 90 basis points. Profit after tax before minority interest rose 64% to Rs 215 crore, while Q2 EBITDA increased 34% to Rs 228 crore and the quarterly margin was 14.7%.
Management said Q2 EBITDA margin declined marginally from the preceding quarter because rising input costs and related recoveries from original equipment manufacturers increased both revenue and costs. It said most raw-material cost increases were recovered, generally with a lag of up to one quarter, but this mechanism could reduce the EBITDA percentage margin by about 30-40 basis points even when the absolute rupee cost is recovered.
Management said it remained confident of meeting its previously stated FY28 absolute EBITDA target of about Rs 1,000 crore. As of September 2026, Lumax had free cash reserves of Rs 400 crore, long-term debt of Rs 442 crore and a debt-to-equity ratio of 0.26, alongside its FY27 capital-expenditure plan of around Rs 300 crore.
Conclusion
The FY27 guidance upgrade reflects a change from the initially implied 12%-14% growth range to management’s current 20%-25% range, supported by 34% H1 revenue growth and increases across Advanced Plastics, Mechatronics and Alternate Fuels. The Rs 1,879 crore order book, with 86% scheduled for FY28 and FY29, provides a disclosed base of future execution beyond the current year.
The next measures to watch are whether H2 FY27 growth falls within management’s 15%-20% expectation, the effect of input-cost pass-throughs on EBITDA margin, and the start of production at H2 FY27 expansion projects. Management also plans to begin commissioning the Manesar plant in Q3 FY28 and continues to target about Rs 1,000 crore of EBITDA in FY28.